Selling a Parent's Home to Pay for Assisted Living in San Joaquin County
When a parent suddenly needs assisted living or memory care, families often run into the same financial problem:
The monthly cost of care starts now, but much of Mom or Dad's wealth may still be tied up in the house.
That creates an urgent question:
How quickly can we turn the home into money that can help pay for care?
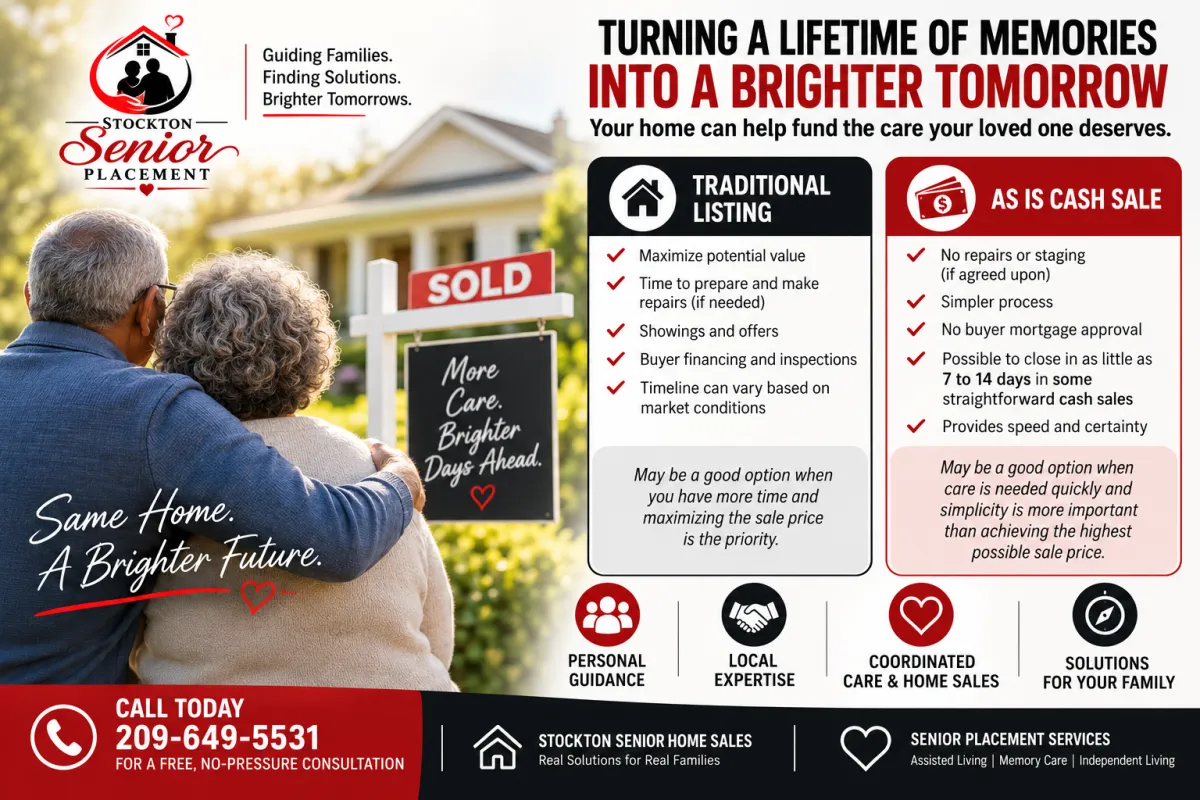
For families in Stockton and throughout San Joaquin County, there are usually two main paths: selling the home traditionally or considering an as is sale designed for a faster closing.
Neither option is automatically better.
The right choice depends on how quickly care is needed, the condition of the property, how much equity is available, who has legal authority to sell, and whether programs such as Medi Cal are part of the family's long term care plan.
Here's what families should know before making that decision.
Why a Traditional Home Sale May Not Match an Urgent Care Timeline
A traditional listing is generally designed to expose a property to the open market and pursue the strongest available price.
That can be an excellent option when the family has time.
But preparing a longtime family home for sale may involve cleaning, removing belongings, making repairs, taking photographs, listing the property, scheduling showings, evaluating offers and completing the buyer's financing and inspection process.
Once an offer is accepted, escrow still has to close.
The entire process can take weeks or months depending on the property, buyer, financing, and market conditions.
For a family planning ahead, that may be perfectly acceptable.
For a family being told that Mom is being discharged from the hospital in a few days and can no longer safely live alone, the timeline may be very different.
How an As Is Home Sale Can Work
An as is sale can eliminate many of the steps associated with preparing a house for the traditional market.
Depending on the agreement, the seller may be able to avoid repairs, renovations, and staging. A cash transaction can also eliminate the buyer's mortgage approval process.
In a straightforward transaction with clear title and someone who already has legal authority to sell the property, closing may sometimes be possible in approximately 7 to 14 days.
That is not a guarantee.
Title problems, liens, probate, trusts, reverse mortgages, questions about signing authority and other issues can extend the timeline.
The tradeoff is important:
Speed and convenience may come at the cost of a lower sale price.
A cash buyer typically needs to purchase below the property's potential retail value.
That is why families should compare their options rather than automatically choosing the fastest one.
Traditional Listing vs. As Is Sale: Which Is Better?
Think about the decision this way.
A traditional listing may make more sense when:
• The family has time before care must be funded
• The home is in reasonably good condition
• Maximizing the sale price is the priority
• The family can manage repairs, cleaning, and showings
• Carrying the property for a longer period is financially manageable
An as is sale may make more sense when:
• A parent needs care immediately
• Savings are being depleted by private pay care
• The property needs substantial repairs
• The family does not want to clean out or renovate the house
• Certainty and speed are more important than achieving the highest possible sale price
The goal should not be simply to sell fast.
The goal should be to determine which option leaves the family in the strongest position to pay for care.
What Can Delay the Sale of a Parent's Home?
Before focusing on the closing date, determine who actually has authority to sell.
This becomes especially important when a parent has lost capacity or has died.
If the Home Is in a Living Trust
A properly funded living trust may allow the acting trustee to sell the property without going through a full probate proceeding, assuming the trust gives the trustee the necessary authority.
Review the trust documents and current title before proceeding.
If a Parent Has Lost Capacity
A family member cannot sell a parent's home simply because they are the son or daughter.
There must be valid legal authority.
Depending on the circumstances, that authority might come from an existing power of attorney, trust, or court appointed conservatorship.
If the Owner Has Died
The property may be controlled by a trust, estate proceeding, or another form of ownership.
California probate sales can involve specific notice or court procedures depending on the representative's authority and the circumstances of the estate.
Families dealing with any of these situations should have the appropriate estate planning or probate attorney review the documents before signing a sale contract.
What If There's Still a Mortgage?
Having a mortgage does not normally prevent the home from being sold.
Escrow obtains the payoff amount, and the loan is generally paid from the sale proceeds at closing.
What matters to the family is the net equity remaining after the mortgage, transaction expenses and other amounts that must be paid.
What If There's a Reverse Mortgage?
A reverse mortgage requires additional attention.
Before deciding how much money will actually be available for care, obtain a current payoff statement from the loan servicer.
Do not make placement decisions based only on the home's estimated market value.
The number that matters is the family's estimated net proceeds after closing.
Do We Have to Empty the House?
Not necessarily.
Some as is buyers will agree in writing to purchase a property with unwanted furniture or belongings remaining.
Others will not.
If leaving personal property behind is important to your family, make sure that arrangement is specifically stated in the purchase agreement rather than assuming that the words “as is” include everything inside the house.
Will We Owe Taxes When the Home Is Sold?
Possibly, but the sale price itself does not determine the tax bill.
Capital gain generally depends on factors including the owner's tax basis and applicable exclusions.
A qualifying homeowner may be able to exclude up to $250,000 of gain, or up to $500,000 for certain married couples filing jointly. Inherited property is subject to different basis rules and generally receives a basis based on its fair market value at the owner's death.
Because ownership, trusts, inheritance and individual tax situations differ, families should obtain advice from a qualified tax professional rather than assuming there will or will not be a large tax bill.
What About Medi Cal?
This is especially important in 2026.
California restored asset limits for many Non MAGI Medi Cal programs beginning January 1, 2026. Through June 30, 2027, the general asset limit is $130,000 for one person, with additional allowances depending on household circumstances. California also has special rules involving principal residences, spouses, and long term care.
Selling an exempt home can potentially convert real estate into cash or other assets that are treated differently for eligibility purposes.
California also applies a 30 month lookback to certain transfers for less than fair market value when long term care coverage is involved.
That means a family considering Medi Cal should not sell, transfer or give away a home solely based on general information from a real estate professional or senior placement company.
Talk with a qualified elder law attorney or Medi Cal planning professional before making a transaction that could affect eligibility.
Coordinating the Home Sale With Senior Placement
This is where families often benefit from looking at the entire situation instead of treating the house and care placement as two unrelated problems.
You need to know:
How much will care cost each month?
How much income does Mom or Dad already have?
How much equity is actually available from the home?
How quickly does the family need access to those funds?
Who has legal authority to sell?
Could Medi Cal or another benefit become part of the care plan?
Only then can you intelligently decide how the property should be sold.
Get a Free Home Sale and Senior Placement Consultation
At Stockton Senior Placement and Stockton Senior Home Sales, we help San Joaquin County families look at both sides of the decision.
If your parent needs assisted living or memory care and the family home may need to help pay for it, we can help you evaluate the timeline, explore senior living options, and understand your home sale choices.
You don't have to decide on a cash sale before talking with us.
We'll help you compare whether an as is sale or traditional listing better fits your family's situation.
Call 209 649 5531 for a free, no pressure consultation.
Important Disclaimer: This article is provided for general informational purposes only and is not intended as legal, tax, financial, real estate, or Medi Cal eligibility advice. Laws, program requirements, and individual circumstances can vary. Before making decisions that may affect property ownership, taxes, estate administration, Medi Cal eligibility, or long term care planning, consult an appropriately qualified attorney, tax professional, financial professional, or benefits specialist for advice regarding your specific situation.