How to Pay for Assisted Living When There's No Long-Term Care Insurance
Money is the first wall almost every family hits. Mom or Dad needs more care than you can give at home, you tour a few communities, and then you see the price. $4,500 to $7,000 a month in San Joaquin County is normal. If there is no long-term care insurance sitting in the background, it feels like the whole plan just died in the parking lot.
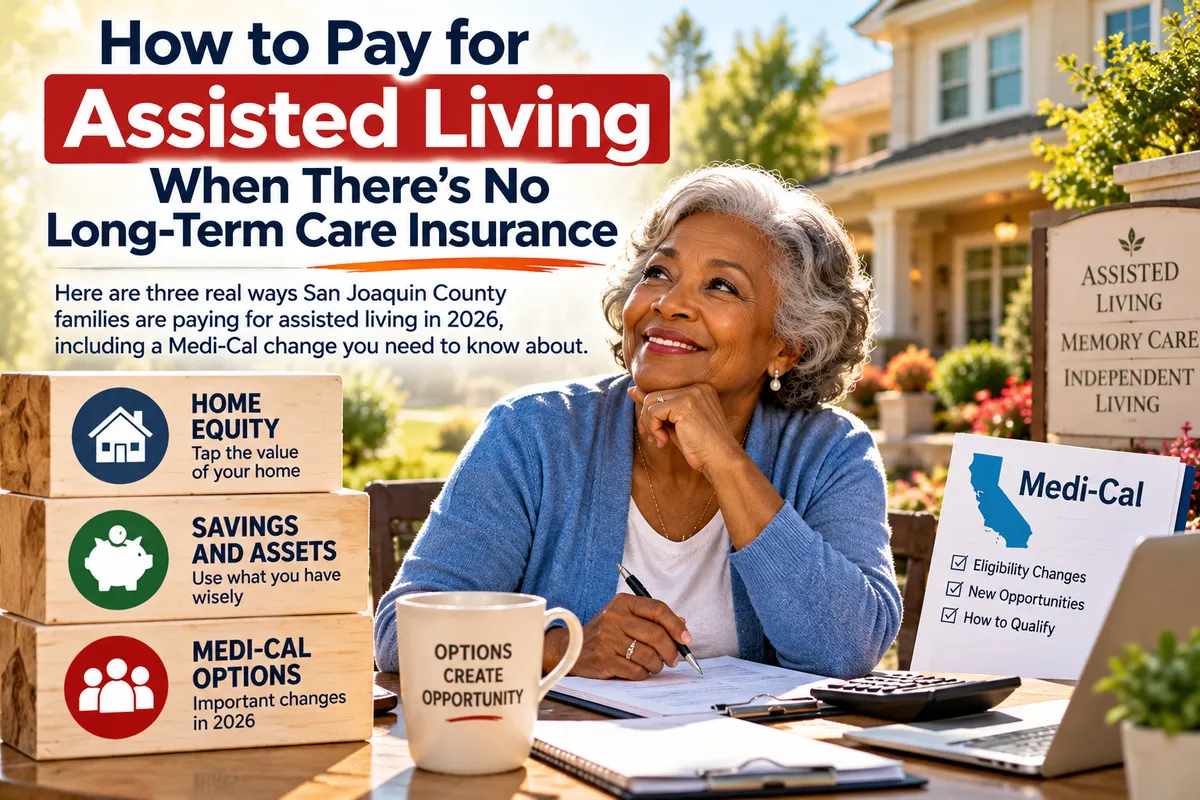
It didn't. Most of the families I place into care every month are paying for it without a long-term care policy. They are using one of three tools: Medi-Cal, VA benefits, or the equity sitting in the family home. Here is how each one actually works, and what changed for 2026 that you need to know before you wait too long.
Option 1: Medi-Cal, and the Change Everyone Needs to Know About Right Now
Regular Medi-Cal health coverage in California doesn't look at your assets. Most people already know that. What most families don't know is that the Medi-Cal programs that pay for long-term care, the ones that cover a nursing facility or in-home support, are different, and the rules just changed.
Starting January 1, 2026, California brought back the asset limit for these long-term care programs. It's set at $130,000 for an individual, with another $65,000 added for each additional person counted in the household. California also brought back the 30-month look-back period, which means the state can look at any assets given away or transferred in the 30 months before you apply.
For a few years, California had dropped both of these rules, which made planning simple. That window closed. If your parent has savings, a second property, or investments above the new limit, or if the family has been thinking about transferring assets to qualify, the clock now matters again. This is not something to figure out on your own with a Google search the week you need placement. An elder law attorney who works in Medi-Cal planning can tell you in one meeting whether your parent qualifies now, what the look-back period means for your specific situation, and what can legally be done about it. I am not an attorney and this isn't legal advice, but I can tell you who to call, and I can tell you that waiting costs families options every single time.
Here's the part families miss: Medi-Cal doesn't pay for room and board in most assisted living settings the way people assume. It's more commonly used for in-home care, nursing facility stays, and through specific waiver programs for board and care in some cases. Whether it applies to your situation depends entirely on the level of care needed and which setting you're looking at. This is exactly why a placement conversation and a Medi-Cal eligibility conversation need to happen together, not separately.
Option 2: VA Aid and Attendance
If your parent or their spouse served during a wartime period, this benefit is one of the most underused tools in senior care. Aid and Attendance is a monthly cash benefit added on top of a VA pension, and it exists specifically to help pay for the cost of daily care, whether that's in-home help or a community.
For 2026, the numbers look like this. A single wartime veteran can receive up to $2,424 a month. A veteran with one dependent can receive up to $34,488 a year. Two married veterans who both qualify can receive up to $46,143 a year combined. A surviving spouse of a veteran can receive up to $1,558 a month. There's also a net worth limit for eligibility, set at $163,699 for 2026.
That is real money, and it stacks with other income. I've had families who assumed their dad's small pension and social security check ruled him out of any help, and it turned out Aid and Attendance closed most of the monthly gap for assisted living. The application process is slow and the paperwork is a headache, which is exactly why most families never apply. A VA-accredited claims agent or a veterans service officer, many of whom work for free through the county, can walk you through it. Don't leave this money on the table because the form looks intimidating.
One thing to plan around: VA claims are not fast. A first-time Aid and Attendance claim commonly takes three to six months to process, sometimes longer. That doesn't mean it isn't worth filing, it means you should file the moment care becomes a real possibility, not the week you actually need the money. Families who file early often have the benefit approved and arriving right around the time they need it most. Families who wait until the crisis end up private paying for months while the claim works through the system.
Option 3: Selling the Family Home
For a lot of families in San Joaquin County, the house is the plan, whether they've said it out loud yet or not. Mom's house is paid off or close to it, nobody is living in it once she moves to care, and the equity sitting in those walls is worth more than any benefit program will provide.
The problem is timing. A traditional home sale takes 60 to 90 days once you count prepping the house, listing it, waiting for offers, and closing escrow. Families in a real placement crisis, someone getting discharged from the hospital this week, don't have 90 days. This is where an as-is cash sale becomes the practical answer. You're not fixing anything, not staging anything, not waiting on a buyer's financing to fall through. You sell the house the way it sits, close in as little as 7 to 14 days, and use the proceeds to fund care immediately while the rest of the estate gets sorted out properly.
This also matters for the Medi-Cal conversation above. A home sale changes what counts as an asset, so this decision and the Medi-Cal eligibility conversation need to happen in the right order, not backwards.
Mistakes That Cost Families Money
The biggest mistake is waiting until the crisis to start asking questions. I've watched families lose weeks, sometimes months, because they assumed Medi-Cal would take care of everything, only to find out during an application that a transfer made two years ago is now inside the look-back window, or that the setting they picked isn't one Medi-Cal covers.
The second biggest mistake is assuming a parent doesn't qualify for VA benefits because they never talk about their service, or because a spouse never served in combat. Aid and Attendance eligibility is based on wartime service dates, not combat exposure, and a lot of families rule themselves out without ever checking.
The third mistake is listing the house the traditional way when the family needed cash in three weeks, not three months. A regular listing brings in repair requests, inspection contingencies, and buyers who back out. None of that helps you when Mom is sitting in a hospital bed waiting for a discharge plan.
Which Option Fits Your Family
Most families end up using more than one of these at the same time. Aid and Attendance covers part of the monthly cost, home sale proceeds cover the rest while Medi-Cal eligibility gets sorted out, or a short-term private pay bridge covers the first few months while a VA claim is in process. There isn't one right answer, there's the right combination for your parent's specific numbers, timeline, and level of care.
What there isn't time for is figuring this out for the first time during a hospital discharge or a fall that just happened. If your family is even thinking about this, the conversation should happen now, while you have time to plan instead of react.
We handle placement, the paperwork side of Medi-Cal and VA referrals, and the property sale, under one roof, because families dealing with an aging parent don't have the bandwidth to coordinate three separate companies who've never talked to each other. If you want to know what your specific numbers look like, call for a free placement and funding consultation. We'll tell you straight what you qualify for and what your timeline actually is.